Stress-Test Your Acquisition Playbook
Every acquisition begins with a convincing story about the future. The Investment Thesis sets out the strategic ambition: new customers, additional capabilities, reduced costs, or accelerated growth. The search identifies potential targets, discussions establish whether a transaction is possible, and the investment case translates those ambitions into financial forecasts. Eventually, the board approves the acquisition and the deal moves towards closing. But how much of that projected value has actually been tested by the people expected to deliver it?
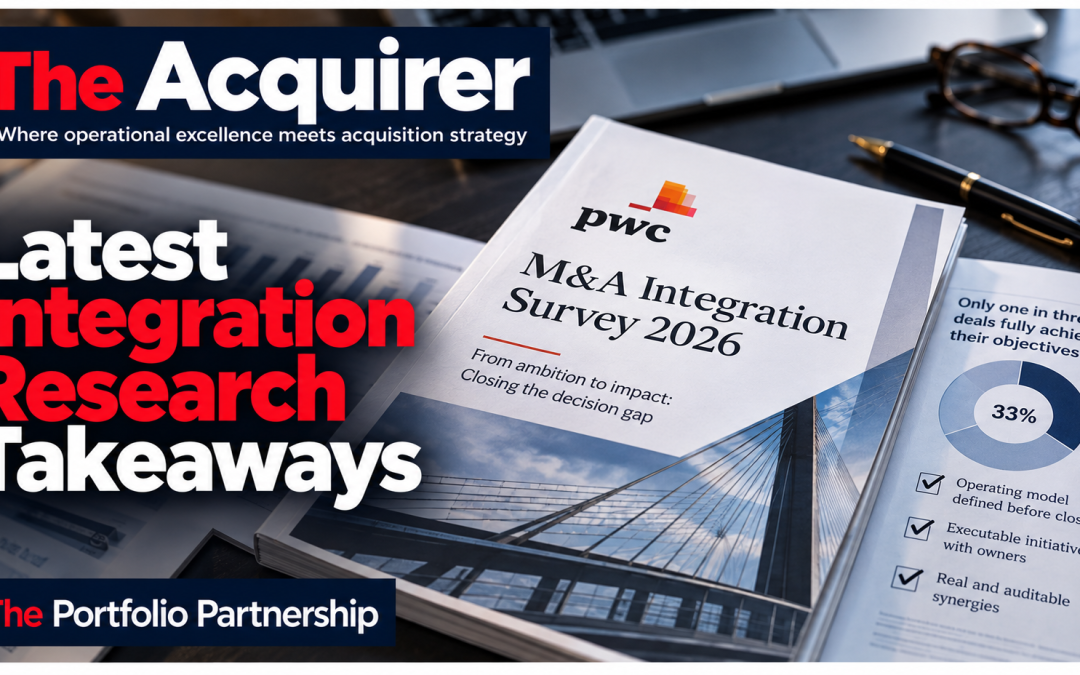
PwC’s 2026 M&A Integration Survey raises that uncomfortable question. Based on responses from 530 executives and senior dealmakers at companies with at least $1 billion in annual revenue, the survey found that only about one in three respondents fully achieved all their prioritized deal-thesis objectives. That does not mean the other deals destroyed value. It does suggest that the distance between an attractive acquisition thesis and a successful operating outcome remains considerable.
The implications are operational, not just financial
One of PwC’s most useful ideas is the “decision gap”: the space between the value imagined in the deal thesis and the operating decisions necessary to produce it. A board may approve a cross-selling opportunity without settling who owns the customer, whether the sales team has the right expertise, or how incentives will work. Procurement savings can look compelling before anyone tests supplier contracts, service requirements, or the cost of changing systems.
The survey found that, among respondents pursuing revenue acceleration, 71% of the successful group defined relevant operating-model elements before closing, compared with 44% of the limited-success group. This is a correlation in self-reported research, not proof that one practice caused success. But it supports a principle we see repeatedly: operating choices cannot be postponed until the deal is done.
Consider a buyer acquiring a specialist services business for its client relationships and technical expertise. The deal model assumes back-office savings and rapid cross-selling. But the founder may personally hold the largest accounts, clients may value the target’s independence, and the buyer’s salesforce may not know how to sell the acquired services. An operator will ask which relationships must be preserved, which capabilities need investment, and what can safely be combined. Those answers should feed directly into the Post-Acquisition Integration Plan and, where material influence the valuation, deal structure, or even the decision to proceed.
Translate the thesis into work someone can own
PwC reports that 59% of successful acquirers had fully translated value drivers into executable initiatives with owners, timelines, and dependencies before integration, versus 28% of limited-success acquirers. That is a meaningful distinction. “Capture procurement synergies” is a line in an investment case. Identifying the supplier categories, the executive accountable, the investment needed, and the date by which savings will appear is a plan.
The discipline must extend to measurement. In the survey, 62% of successful acquirers were very confident their reported synergies were real and auditable, compared with 27% of limited-success acquirers. Operators and finance should agree the starting baseline before the deal closes, separate genuine improvements from ordinary trading movements, and track the cost of delivering each benefit. A saving that requires a costly systems migration or disrupts customer service is not the same as cash in the bank.
And then there are the people. Only 16% of respondents reported assessing leadership and talent before signing or undertaking people and organizational diligence. In a founder-led business, the managing director may also be the principal salesperson, recruiter, and problem solver. Ask what breaks if that person steps away for a month. Then ask who has the capacity to run the existing business while integration absorbs management attention. This is not an argument for replacing people; it is an argument for testing dependency and protecting the day job.
Stress-Test Your Acquisition Playbook
Rather than treating the research as another reminder that integration is difficult, use it to challenge your own acquisition process. Here are six questions I would put to any leadership team pursuing acquisitions:
1. Are operators involved before the deal becomes difficult to change?
Put the investment thesis in front of a small Operators Bench before the Letter of Intent. Give each person two or three specific assumptions to test, rather than inviting everyone to every deal meeting. Ask what evidence would change their mind. An acquisition team does the work; a committee merely reviews it.
2. Have we described the business under our ownership?
Build a first-pass picture of the business under your ownership: what will you PRESERVE, CHANGE, COMBINE, or REMOVE? For each proposed change, mark what is supported by evidence and what is still an assumption. Preserve the capabilities and relationships you paid for before chasing efficiencies that might damage them.
3. Are we capturing and managing integration priorities as they emerge?
The Integration Priorities Register is a living record of the actions, risks, opportunities, and decisions identified throughout the acquisition process. It captures emerging priorities, assigns ownership, and identifies the evidence still required. These findings inform the evolving Post-Acquisition Integration Plan and, where material should influence valuation, deal structure, and the decision to proceed. Are we maintaining this discipline throughout the acquisition process?
4. Can every material value driver be turned into an accountable initiative?
For each benefit, identify an accountable owner, a baseline, dependencies, investment required, implementation cost, and timing. Does the investment case reflect the full cost of delivering the promised benefit, including management time, systems changes, and potential disruption to the existing business? Feed these costs and risks back into the investment paper and price.
5. Have we stress-tested leadership capacity and cultural friction?
Identify keyperson and customer dependencies, decision-making differences, and where the leadership bench is thin. Do not mistake a cultural fit discussion for a few interviews about values: test how the two businesses actually make decisions, resolve disagreements, and treat customers. For example, what happens when one business makes decisions locally and quickly, while the other requires several layers of approval?
6. Will we be able to prove the value was created?
Establish a pre-close baseline, measurable milestones, and a finance-led benefits-tracking process linked to the Integration Priorities Register. Review whether benefits have reached the P&L or cash flow, not simply whether integration tasks are marked complete. Assign an owner to each unresolved assumption and revisit it at every approval gate.
The Operator’s Tip
Before signing the Letter of Intent, convene a short operator challenge session. Ask: “If we owned this business tomorrow, what would we preserve, change, combine, or remove—and why?” Then ask: “Who will deliver it, what will it cost, and what could go wrong?” Record the answers in the Integration Priorities Register: priority, action or decision required, evidence or assumption, owner, dependency, and next step. The objective is not a polished Day One slide deck. It is to discover what the buyer still does not know while the deal can be reshaped.
A Post-Acquisition Integration Plan should influence target evaluation, the investment paper, valuation, negotiation, due diligence, and approval—not appear as a separate exercise after ownership changes. Update it as new evidence emerges. If a critical assumption fails, the response may be to change the plan, renegotiate the price, attach a condition to approval, or walk away. That is disciplined acquisition thinking, not deal obstruction.
The challenge for acquirers
PwC studied large-company transactions, so its percentages should not be applied mechanically to founder-led and lower-middle-market acquisitions. But smaller businesses may be even more dependent on a few customers, managers, and informal processes. That makes the operating questions more urgent, not less.
The deal team can secure the asset. Operators must deliver the return. If your acquisition playbook cannot answer these six questions with named owners and credible evidence, perhaps the next investment should be in the playbook itself—before the next acquisition.
Appointments: email Ian@TPPBoston.com
Research source and note
PwC, “2026 M&A Integration Survey: How leading acquirers turn M&A strategy into measurable value,” https://www.pwc.com/us/en/services/consulting/deals/library/ma-integration-survey.html. Survey of 530 executives and senior dealmakers at organizations with annual revenue of $1 billion or more. Findings are respondent-reported associations, not causal estimates. The specialist-services example is illustrative.